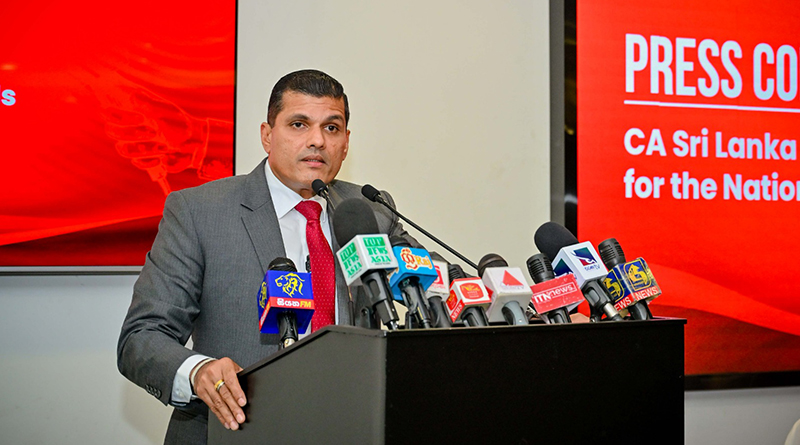
The Institute of Chartered Accountants of Sri Lanka (CA Sri Lanka) on Wednesday outlined its comprehensive proposals submitted to the Government of Sri Lanka for the National Budget 2027 at a press conference. The proposals highlighted the need for a more efficient, equitable and sustainable approach to revenue mobilisation, prioritising improved tax compliance, digital transformation and economic formalisation over excessive reliance on higher statutory tax rates.
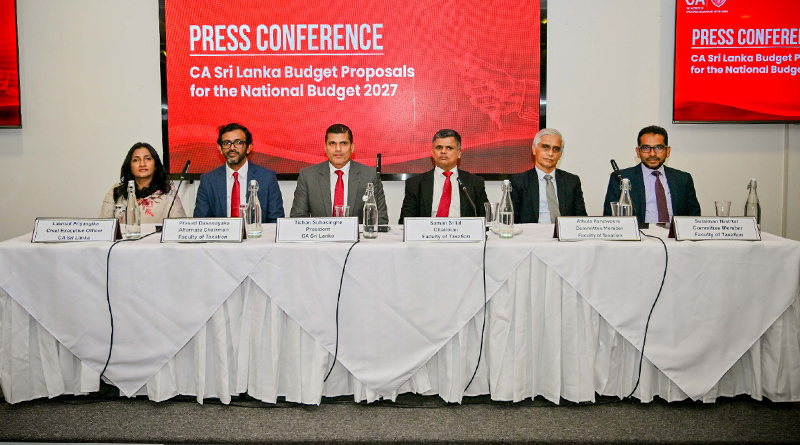
The press conference was attended by CA Sri Lanka President Tishan Subasinghe, Chief Executive Officer Lakmali Priyangika, Chairman of the Faculty of Taxation Saman Sri Lal, Alternate Chairman Prasad Dasanayaka, and Faculty members Athula Ranaweera and Sulaiman Nisthar. The event provided a platform to present CA Sri Lanka’s proposals for the National Budget 2027, outlining recommendations aimed at strengthening tax administration, enhancing compliance and supporting sustainable revenue mobilisation.
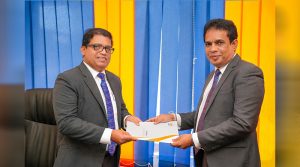
The proposals, which were formally submitted to the Secretary to the Ministry of Finance, Dr Harshana Suriyapperuma, in September 2026 at the Ministry of Finance, are anchored on three complementary objectives: mobilising additional revenue without excessive reliance on higher statutory tax rates; modernising tax administration and improving voluntary compliance; and strengthening the investment, business and institutional environment required for sustainable growth.
CA Sri Lanka highlights the fragility of Sri Lanka’s current revenue structure, which remains heavily dependent on indirect taxation. The Institute noted that this imbalance places a disproportionate burden on consumers and can contribute to informal economic activity. It therefore proposes a clear hierarchy for revenue mobilisation, with statutory rate increases considered only after other avenues have been exhausted.
The proposed hierarchy is:
- Improve compliance with existing taxes;
- Identify economic activity that currently remains untaxed;
- Reduce revenue leakages;
- Broaden the tax base through digitalisation and better information;
- Review and rationalise tax exemptions; and
- Only then consider broad statutory rate increases.
This approach, the Institute believes, would enable Sri Lanka to strengthen revenue mobilisation while minimising unnecessary pressure on compliant taxpayers and businesses.
CA Sri Lanka therefore recommends establishing an integrated data ecosystem through the National Taxpayer Information Network (NTIN) and Universal Business Identification Number (UBIN), connecting information from Customs, VAT transactions, corporate ownership, financial accounts, property records and other relevant datasets.
The Institute proposes that UBIN, NTIN and electronic invoicing should be developed as part of the wider World Bank-supported digital transformation agenda, ultimately contributing towards a single digital economic identity that can improve both revenue administration and the delivery of government services.
The proposals call for Sri Lanka to move progressively from volume-based enforcement towards a formal Compliance Risk Management framework, classifying taxpayers according to low, medium and high risk.
As part of this transition, CA Sri Lanka proposes an AI-assisted Tax Compliance Risk Engine to identify potential high-risk cases involving shell companies, unexplained wealth, circular transactions and VAT fraud. The system would function as a selection and risk-identification tool rather than a final determinant of tax liability, ensuring that technology supports professional assessment and due process rather than replacing them.
The Institute also recommends strengthening the existing High-Wealth Individual (HWI) Compliance Programme through a formal wealth-to-income risk model.
To address gaps between actual economic capacity and reported income, the proposals recommend enhanced monitoring of financial assets, cryptocurrencies and insurance investments through annual information returns.
CA Sri Lanka further proposes a VAT Intelligence Programme, initially as a pilot initiative, using objective indicators such as electricity consumption, bank deposits and point-of-sale (POS) data to identify potential compliance risks in high-risk, cash-intensive sectors, including gold and auto-parts businesses.
The Institute recommends the phased introduction of mandatory electronic invoicing, beginning with large VAT taxpayers and high-risk sectors before progressively expanding across the wider business community.
It also proposes automated Customs–Import Data Reconciliation, comparing Customs values and landed costs against inventory, sales, VAT and income tax returns to identify potential revenue leakages, particularly in import-dependent sectors.
CA Sri Lanka proposes revising the Advance Personal Income Tax (APIT) threshold to Rs. 200,000 per month, providing relief to middle-income earners.
While recognising the fiscal impact, CA Sri Lanka believes the measure could stimulate economic activity and improve disposable income amid continuing inflationary pressures. The proposals therefore emphasise that the fiscal cost should be considered alongside the potential economic benefits of increased consumption and formal economic activity.
To support formalisation and sustainable growth, CA Sri Lanka proposes a tiered corporate income tax structure based on annual turnover.
The structure would be supported by a proportionality principle in tax compliance, recognising that smaller businesses should not face the same administrative burden as larger corporations.
Micro businesses should be able to maintain simplified records, while small and medium-sized businesses could progressively adopt standardised digital templates. The objective is to encourage businesses to formalise and grow without excessive compliance requirements inadvertently pushing smaller enterprises into informality.
The Institute also recommends that the Central Bank encourage financial institutions to rely, where appropriate, on audited financial statements and tax returns when assessing credit applications, thereby reducing the need for SMEs to incur additional costs to satisfy lending requirements.
CA Sri Lanka further calls for the urgent expedition of Development Banks’ concessionary lending facilities for SMEs, with access linked to the submission of audited accounts. This would provide much-needed support to businesses facing current cash-flow constraints while simultaneously encouraging stronger financial reporting practices.
The CA Sri Lanka proposals also call for stronger and more transparent capital gains assessments, including a framework under which valuations prepared by accredited independent professionals are formally considered by the Inland Revenue Department (IRD).
For tourism, CA Sri Lanka recommends a dedicated Digital Tourism Booking Framework to address tax-base erosion associated with non-resident digital platforms facilitating accommodation bookings in Sri Lanka.
The framework would seek to capture offshore deductions and related economic value, including booking commissions, franchise royalties and global marketing fees paid to non-resident platforms, ensuring that Sri Lanka’s tax base appropriately reflects the economic activity generated within the country.
CA Sri Lanka also proposes a statutory Right to Self-Correction, allowing taxpayers to correct genuine errors while distinguishing taxpayer-initiated corrections from pre-assessment correction opportunities.
The Institute also recommends establishing an Independent Taxpayer Ombudsman to address complaints relating to administrative treatment, unreasonable delays, communication failures and systemic service issues.
In addition, the proposals call for a Tax Administration Service Charter establishing clear standards for fairness, timeliness, communication and adequate advance notice of compliance requirements. This would help prevent situations where taxpayers face retrospective compliance difficulties following sudden changes in requirements, such as changes to VAT invoice procedures.
CA Sri Lanka also proposes amending the law to allow the Commissioner-General of Inland Revenue to waive or reduce disproportionate interest on just and equitable grounds, where appropriate.
A further holdover provision is proposed to suspend tax collection during the appeal process in qualifying cases. This would help prevent undue financial pressure on taxpayers and reduce the risk of coercive settlements while legitimate disputes are being determined.
The Institute stresses that reform of the Inland Revenue Department (IRD) must go beyond simply filling existing vacancies.
While CA Sri Lanka calls for the urgent filling of 223 senior-level vacancies, it also recommends lateral recruitment for specialised technical positions, including data scientists and other digital and analytical professionals.
Continuous professional development should form an integral part of this transformation, including training partnerships with professional bodies such as CA Sri Lanka in specialised areas such as international taxation and transfer pricing.
The proposals also recommend establishing a permanent Tax Policy and Revenue Analytics Unit within the Ministry of Finance to undertake tax-gap analysis, tax expenditure evaluation and revenue forecasting.
To strengthen transparency and accountability, the Institute proposes the publication of information relating to tax expenditure, tax arrears and key compliance indicators.
CA Sri Lanka recommends a formal assessment of Sri Lanka’s exposure to the OECD’s 15% global minimum effective tax rate under Pillar Two, together with consideration of a Qualified Domestic Minimum Top-up Tax (QDMTT) to protect the domestic tax base.
The Institute also recommends restoring the real tax share on cigarettes towards the WHO benchmark of 75%, with estimated annual revenue recovery of Rs. 17.3 billion, subject to Treasury validation.
However, CA Sri Lanka stresses the importance of evidence-based policymaking. Estimates relating to cigarette excise reform should be validated against possible illicit-market effects, while potential QDMTT revenue cannot be responsibly estimated without multinational enterprise-level GloBE income data.
Similarly, revenue estimates associated with NTIN, HWI compliance and Customs reconciliation should be supported by formal tax-gap studies.
CA Sri Lanka emphasises that all major tax and revenue proposals should undergo a formal Revenue Impact Assessment before being considered for inclusion in the National Budget.
The Institute urges the Government to give immediate priority to integrated tax data, HWI compliance, Customs–IRD reconciliation and Pillar Two implementation, while progressively building the digital and institutional infrastructure required for a modern revenue administration.

Be First to Comment